Statistical publication

Quarterly authorised deposit-taking institution performance statistics - June 2026 highlights

Published
17 September 2026

Key statistics

Excludes ADIs that are not banks, building societies or credit unions, such as payment providers. The year-on-year change are calculated using the underlying unrounded values.

 June 2025June 2026Year-on-year change
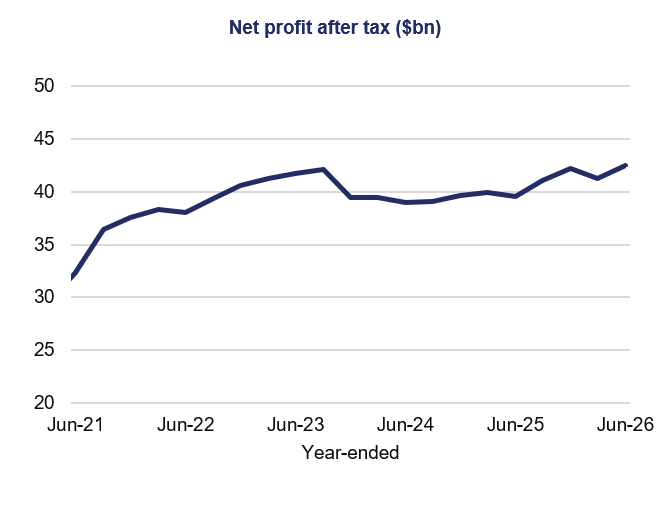
Net profit after tax (year-end) ($bn)39.642.57.5%
Total assets ($bn)6,673.07,074.36.0%
Total capital base ($bn)462.9480.03.7%
Total risk-weighted assets ($bn)2,269.32,339.03.1%
Total capital ratio20.4%20.5%0.13 points
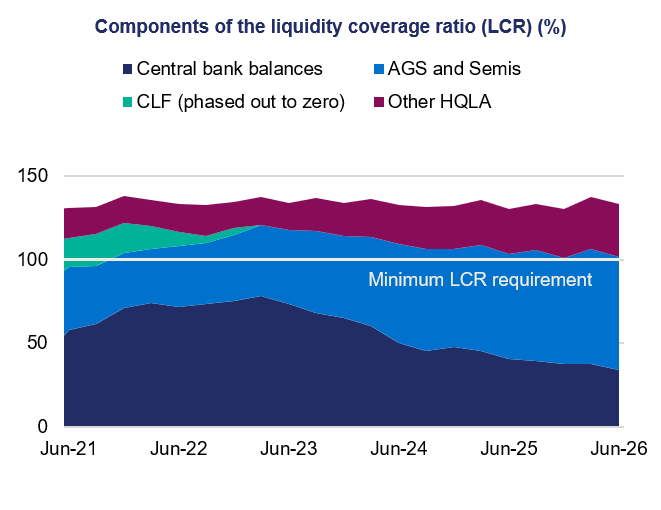
Liquidity coverage ratio130.0%133.0%3.01 points
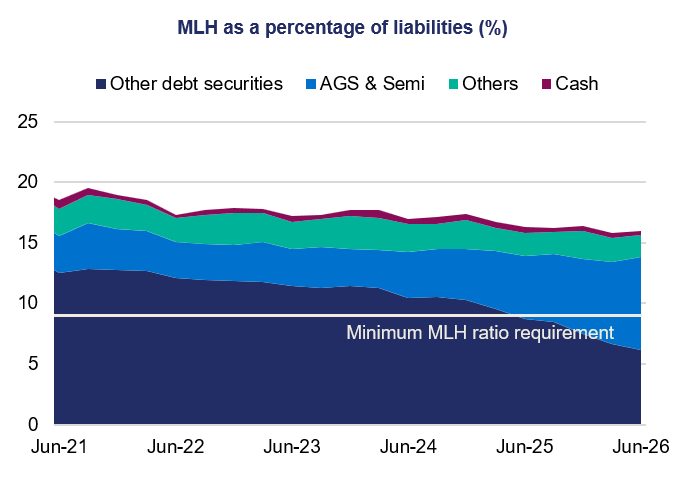
Minimum liquidity holdings ratio16.3%16.0%-0.32 points
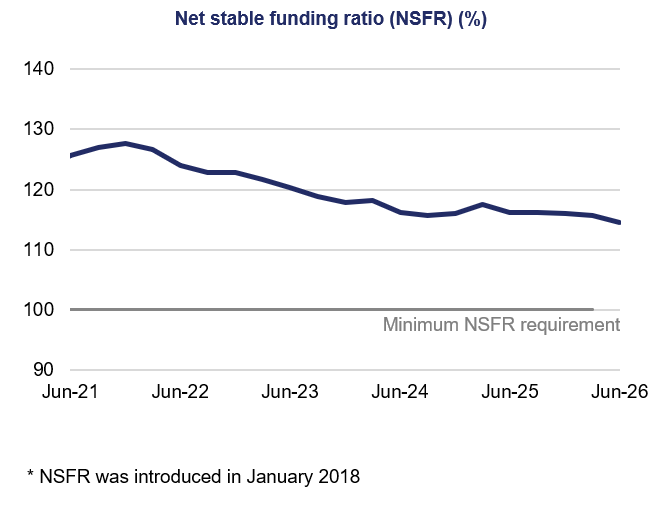
Net stable funding ratio116.2%114.5%-1.67 points

Financial performance

Line chart tracks net profit after tax ($bn) from Jun-21 to Jun-26, using a dark-blue line, horizontal gridlines, and y-axis values from 25 to 50. Profit rises from about $32bn to a mid-2023 peak near $42bn, drops to roughly $39bn, then recovers with fluctuations to about $42.5bn by Jun-26.
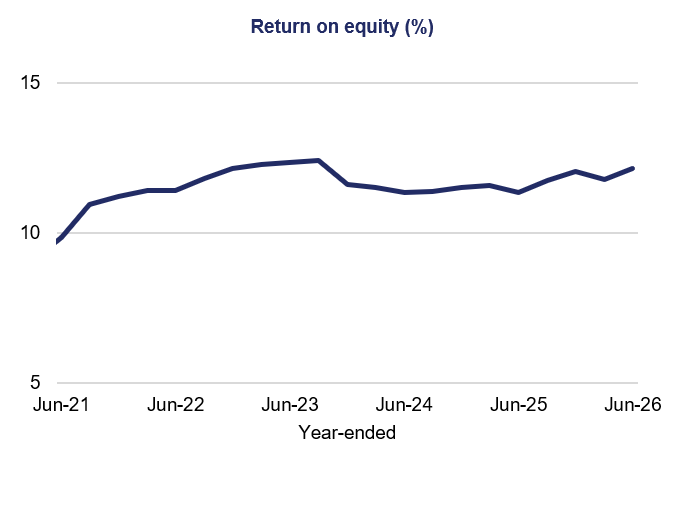
Line chart titled “Return on equity (%)” tracks year-ended ROE from Jun-21 to Jun-26. Navy line rises from about 10% to 12.5% by Jun-23, dips near 11.3% in Jun-24, then fluctuates around 11.5–12.2% through Jun-26.
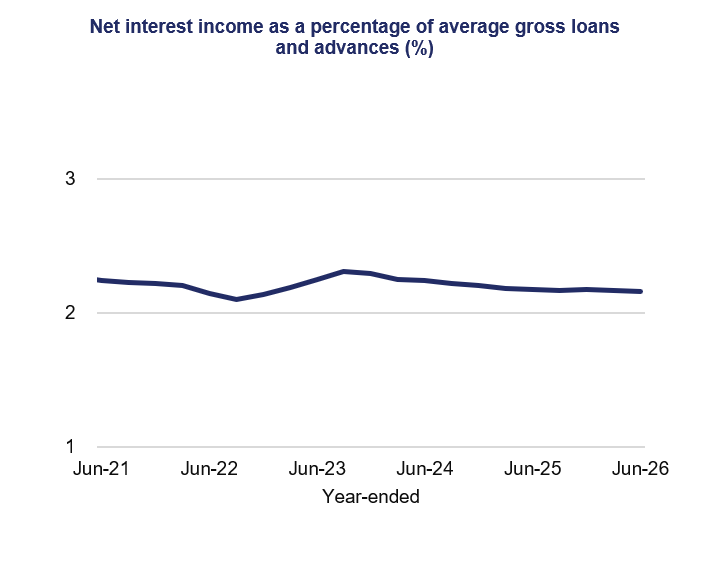
Line graph showing net interest income as a percentage of average gross loans and advances from Jun-21 through Jun-26. Navy line starts near 2.2%, dips to about 2.1% in Jun-22, peaks near 2.3% in Jun-23, then gradually settles around 2.15% by Jun-26.
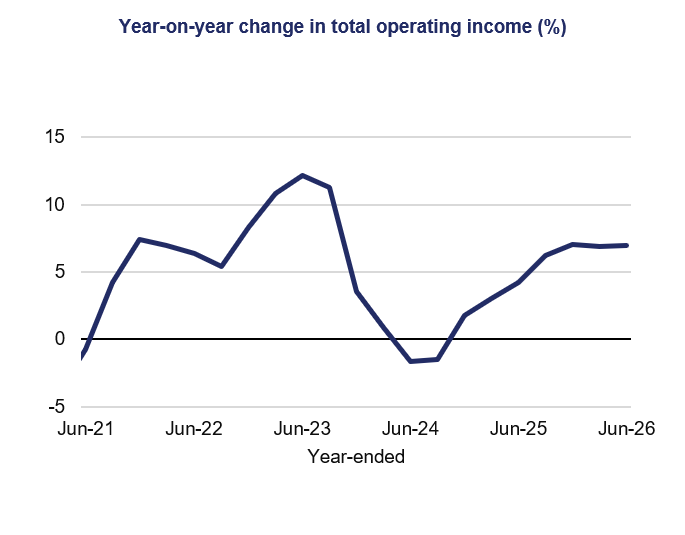
Line chart titled “Year-on-year change in total operating income (%)” tracks annual change from Jun-21 to Jun-26, using a navy line, percentage y-axis, and year-ended x-axis. Values rise from about −1% in Jun-21 to 12% around Jun-23, fall below zero near Jun-24, then recover to roughly 7% by Jun-26.
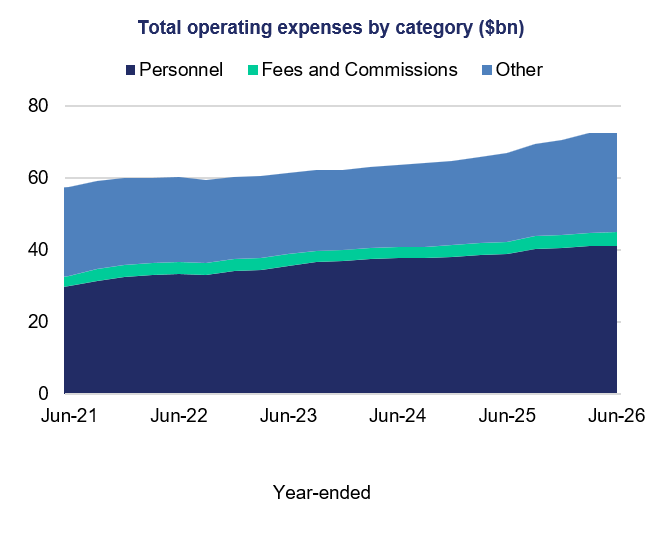
Stacked area chart shows total operating expenses by category ($bn), year-ended Jun-21 through Jun-26. Personnel (navy) rises from about $30bn to $40bn, Fees and Commissions (green) stays near $3–4bn, and Other (blue) brings total expenses from roughly $58bn to $72bn.
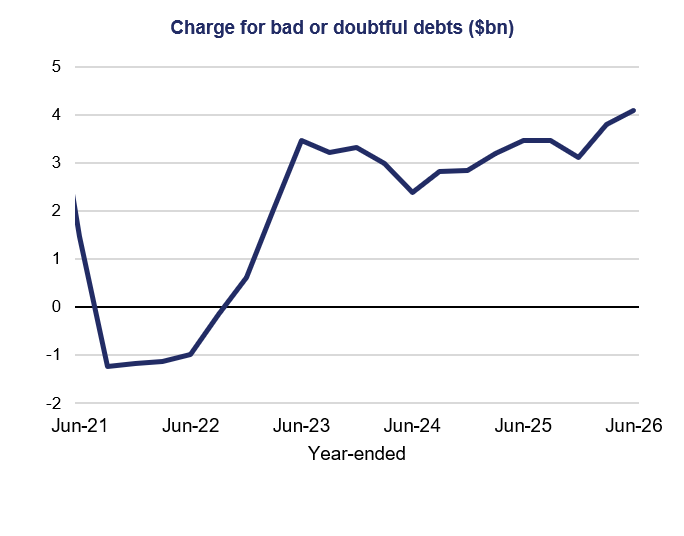
Line chart titled “Charge for bad or doubtful debts ($bn)” tracks year-ended values from Jun-21 to Jun-26. Navy line falls from about $2.1bn to –$1.2bn in Jun-21, then rises with fluctuations to roughly $4.1bn by Jun-26; horizontal zero line marks positive versus negative charges.

Asset quality

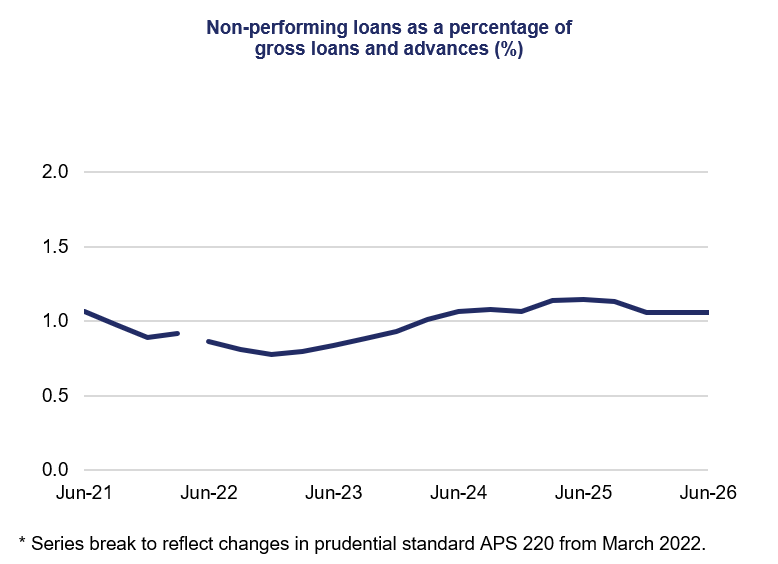
Line chart tracks non-performing loans as a percentage of gross loans and advances from Jun-21 to Jun-26. Rate falls from about 1.05% to 0.8%, rises near 1.1% by Jun-25, then stabilizes near 1.05%; series break appears between Jun-21 and Jun-22 due to APS 220 prudential-standard changes from March 2022.
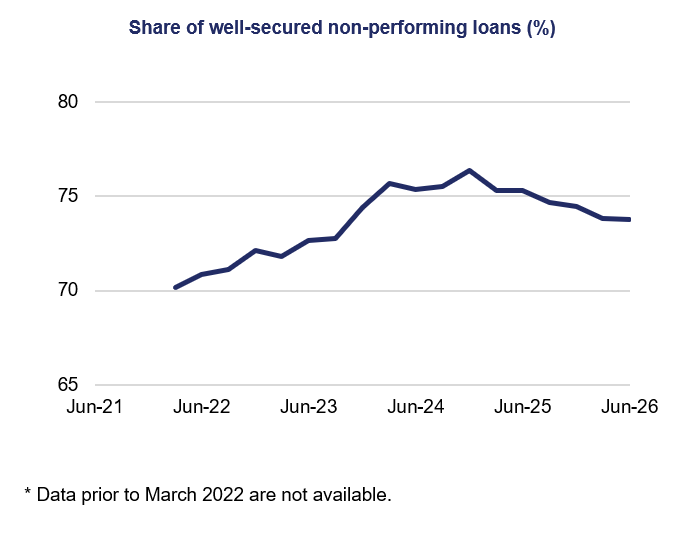
Line chart titled “Share of well-secured non-performing loans (%)” shows quarterly values from Jun-21 through Jun-26, with 65–80% y-axis gridlines and Jun-22–Jun-26 x-axis labels. Navy trend rises from 70% in 2022 to roughly 76% in mid-2024, then declines to about 74% by late 2025; note states data before March 2022 are unavailable.

Capital adequacy

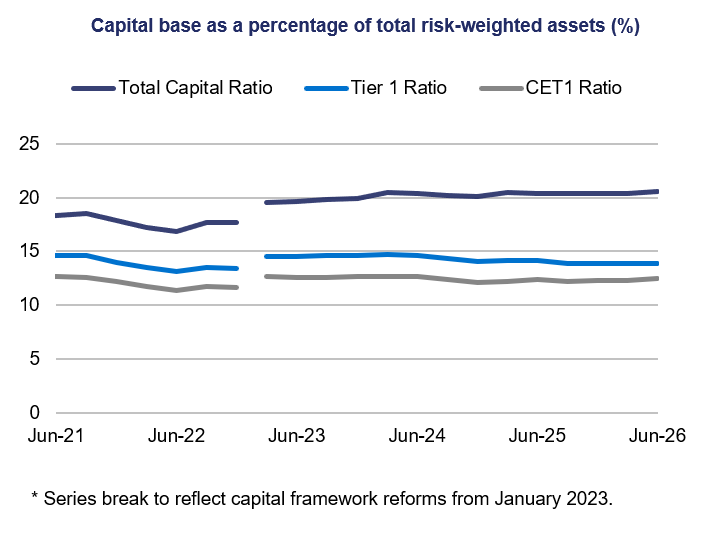
Line chart titled “Capital base as a percentage of total risk-weighted assets (%)” tracks Total Capital Ratio, Tier 1 Ratio, and CET1 Ratio from Jun-21 to Jun-26. Navy Total Capital Ratio rises from about 18% to 20%, blue Tier 1 Ratio stays near 14–15%, gray CET1 Ratio remains near 11–12%, with a visible series break at Jan-23 marking capital framework reforms.
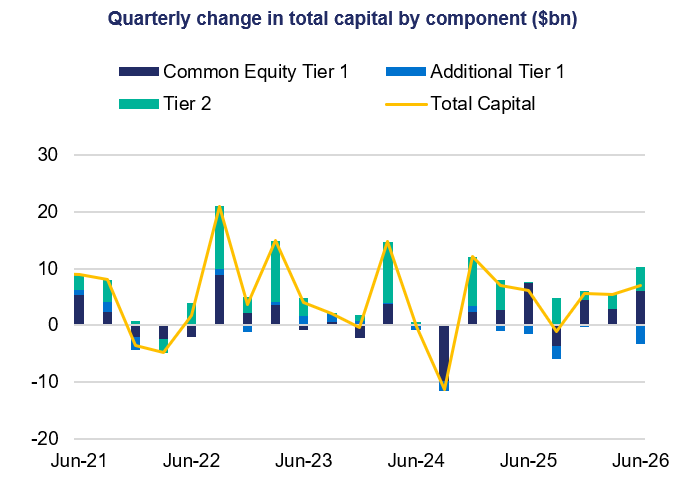
Line-and-stacked-column chart showing quarterly change in total capital by component from Jun-21 to Jun-26, measured in billions of dollars. Navy, blue, and teal bars represent Common Equity Tier 1, Additional Tier 1, and Tier 2, while orange line tracks total capital, peaking near $20 billion in late 2022 and falling to about −$12 billion in mid-2024.
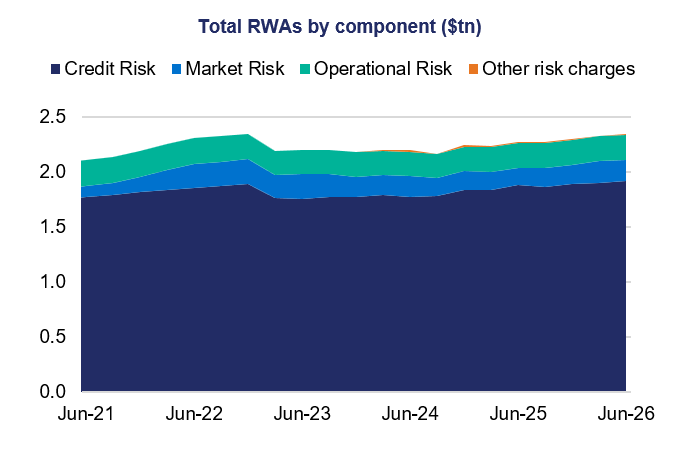
Stacked area chart titled “Total RWAs by component ($tn)” shows risk-weighted assets from Jun-21 through Jun-26. Credit Risk, dark navy, dominates and rises from about $1.75tn to $1.9tn; Market Risk, blue, Operational Risk, teal, and Other risk charges, orange, bring total RWAs from roughly $2.1tn to $2.3tn.
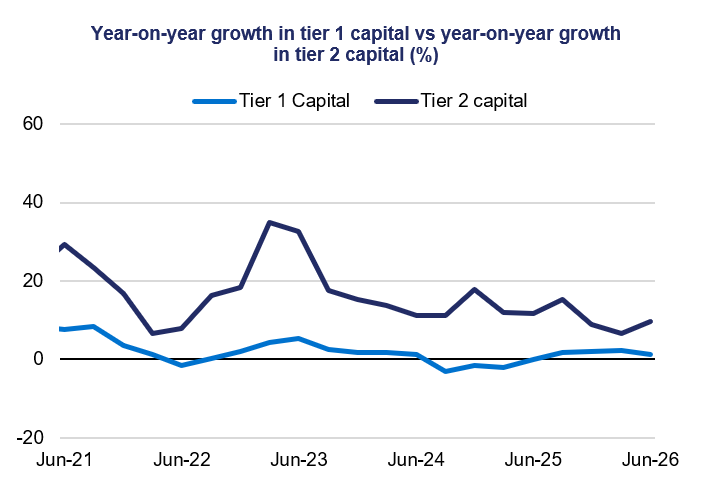
Line chart compares year-on-year growth for Tier 1 and Tier 2 capital from Jun-21 to Jun-26, measured in percent. Blue Tier 1 growth stays near zero, briefly turns negative around Jun-22 and Jun-24, while navy Tier 2 growth peaks near 35% in late 2022 before declining toward single digits by Jun-26.

Liquidity

Stacked area chart shows liquidity coverage ratio (LCR) components from Jun-21 to Jun-26, with a 100% minimum LCR requirement marker. Central bank balances (dark blue) decline after mid-2023, while AGS and Semis, CLF, and Other HQLA maintain total LCR near 125–135%.
Stacked area chart shows MLH as a percentage of liabilities from Jun-21 to Jun-26, segmented into Other debt securities (navy), AGS & Semi (blue), Others (teal), and Cash (magenta). Total MLH declines from roughly 18–19% to 15–16%, while a 9% horizontal marker indicates minimum MLH ratio requirement.
Line chart tracks net stable funding ratio (NSFR) from Jun-21 to Jun-26 against 100% minimum NSFR requirement. Navy line peaks near 128% in late 2021, trends downward to about 114% by Jun-26, and remains above gray benchmark; footnote notes NSFR introduced January 2018.

Financial position

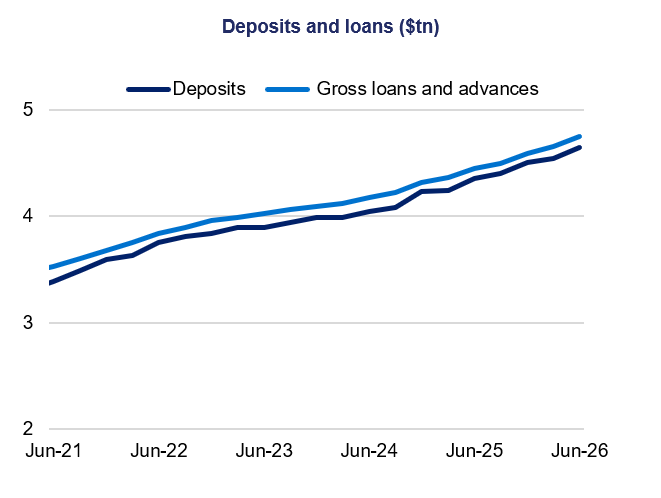
Line chart titled “Deposits and loans ($tn)” tracks deposits and gross loans and advances from Jun-21 to Jun-26. Dark-blue deposits and light-blue loans rise steadily from roughly $3.4–$3.5 trillion to $4.6–$4.8 trillion, with loans remaining slightly above deposits.
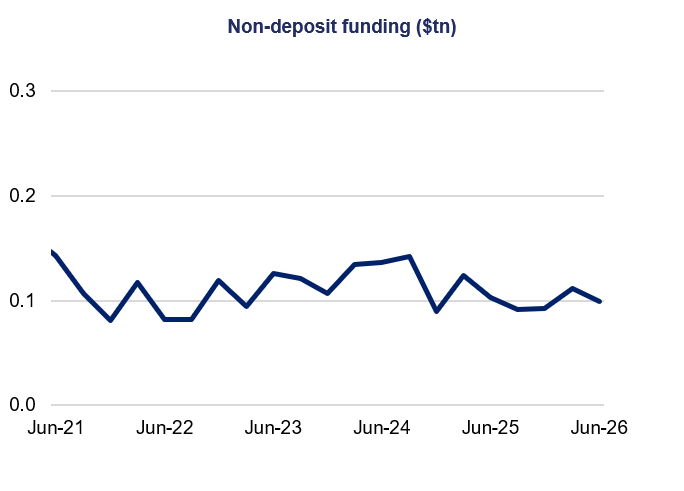
Line chart titled “Non-deposit funding ($tn)” tracks funding from Jun-21 to Jun-26, using a navy line and 0.0–0.3 trillion y-axis scale. Values fluctuate between approximately $0.08tn and $0.15tn, peak near mid-2024, then decline before ending near $0.10tn in Jun-26.

Footnotes

    The Australian Prudential Regulation Authority (APRA) is the prudential regulator of the financial services industry. It oversees banks, mutuals, general insurance and reinsurance companies, life insurance, private health insurers, friendly societies, and most members of the superannuation industry. APRA currently supervises institutions holding around $10.6 trillion in assets for Australian depositors, policyholders and superannuation fund members.